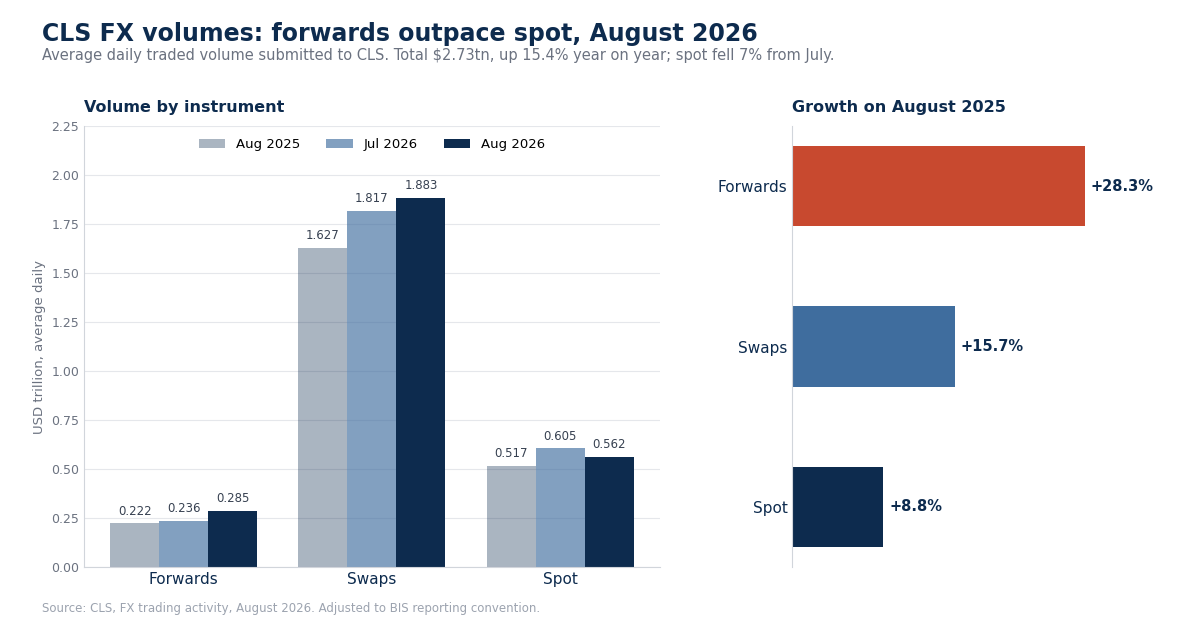
Average daily traded volume submitted to CLS reached USD2.73tn in August 2026, up 15.4% on August 2025. The composition is the more useful signal: forwards grew 28.3% year on year, swaps 15.7% and spot 8.8%, extending a mix shift away from outright directional trading.
Spot fell in absolute terms month on month, from USD0.605tn in July to USD0.562tn in August, a drop of roughly 7% against a 2.7% rise in the overall total. Forwards moved the other way, climbing about 21% from July’s USD0.236tn to USD0.285tn. Spot’s share of CLS-submitted volume is now around 20.6%, against 21.9% a year earlier; swaps hold roughly 69%.
The split matters because the instruments do different jobs. Spot is where directional and transactional flow shows up. Swaps and forwards are funding and hedging instruments: corporates covering receivables, asset managers hedging currency exposure on foreign holdings, banks rolling short-dated funding. Growth concentrated in the latter two points to balance sheet and hedging activity expanding faster than risk-taking, which is a different market to one where spot leads.
For the sell side, that shapes where desk revenue comes from. Swap and forward flow is lower margin per ticket but stickier, and it runs through credit lines and settlement capacity rather than pricing engines. Franchises built around spot e-trading capture less of this; those with strong forwards pricing, collateral and credit intermediation capture more. It also raises settlement exposure at the margin, which is the case CLS itself makes for the service.
Some of the August spot weakness is seasonal, and one month is not a trend. The direction of travel across the year is the part worth watching.
Lisa Danino-Lewis, Chief Growth Officer at CLS, said volumes rose across all instruments over the period.
The usual caveat applies: CLS data reflects executed volumes submitted by its settlement members, adjusted to the BIS convention of counting one side of a trade and one leg of a swap. It is a large, consistent sample of the institutional market, not total global FX turnover.